Independent, published risk assessments for central securities depositories and central counterparties. Promotes infrastructure stability and transparency.
Why commission a Public Risk Assessment?
A Central Securities Depository (CSD) or Central Counterparty (CCP) can commission an independent assessment of its own operations to demonstrate resilience, transparency, and operational excellence. By opting for a Public Risk Assessment, a market infrastructure can obtain a credible, independent validation of its capabilities, to identify gaps to best market practice and allow it to promote infrastructure stability to regulators and investors.
The Public Assessment Advantage
While Thomas Murray conducts proprietary assessments on behalf of global custodians and banks to support asset safety and SEC 17(f)-7 compliance, the Public Risk Assessment is designed as a "deep-dive" analysis for the FMI. Unlike proprietary reviews, the Public programme provides the FMI's management with confidential, detailed feedback and management reports highlighting specific areas for improvement.
These assessments are available in two tiers:
Full Assessment
Offers the deepest level of feedback and provides the right to publish the final report for one year.
Light Assessment
Offers a streamlined feedback process and provides the right to publish the final report for six months.
CSD Risk Assessments
Central Securities Depositories
We evaluate a depository’s capabilities, the quality of its operational infrastructure, and its ability to protect participants and their clients from loss. Our methodology measures CSDs against international best practice standards across core service operational models, financial stability, and risk control frameworks.
- Coverage: More than 140 CSDs monitored on an ongoing basis.
Benchmarking: Comparison against peer markets and global industry standards.
Also available: Cybersecurity ratings and ESG assessments for every CSD. - Eight core risks, each rated from AAA to C:
Asset Commitment, Liquidity, Counterparty, Asset Safety, Asset Servicing, Financial, Operational, and Governance and Transparency.
CCP Risk Assessments
Central Counterparties
Since 2013, our industry-driven programme has assessed how effectively CCPs manage the risks borne by their users. This supports regulatory expectations that firms rigorously monitor the concentration of risk inherent in CCPs.
- Core question: How effectively does the CCP manage the risk that falls on its users?
Coverage: A comprehensive list of covered CCPs is available upon request. - Six risk components:
Counterparty, Liquidity, Asset Safety, Financial, Operational, and Governance and Transparency.
Turn due diligence into a strength
Transparency for users
Provide participants and their clients with an independent, standardised view of your risk management.
Lower due-diligence burden
Regulated firms can rely on a single trusted assessment, reducing costs and administrative friction for both you and your clients.
Benchmarked credibility
Identify where you lead the market and demonstrate your commitment to global best practices.
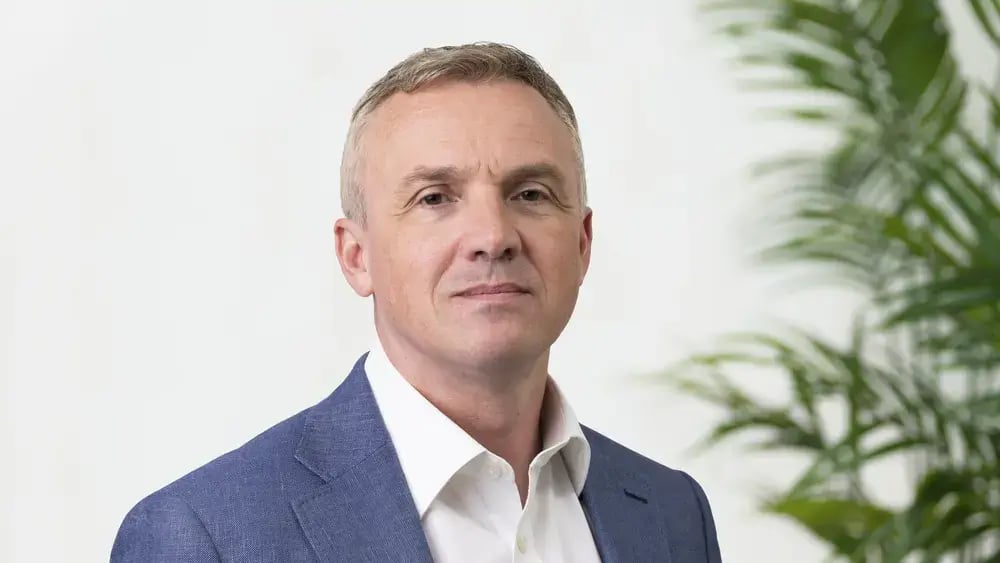
Jim Micklethwaite
Managing Director | Head of FMIs
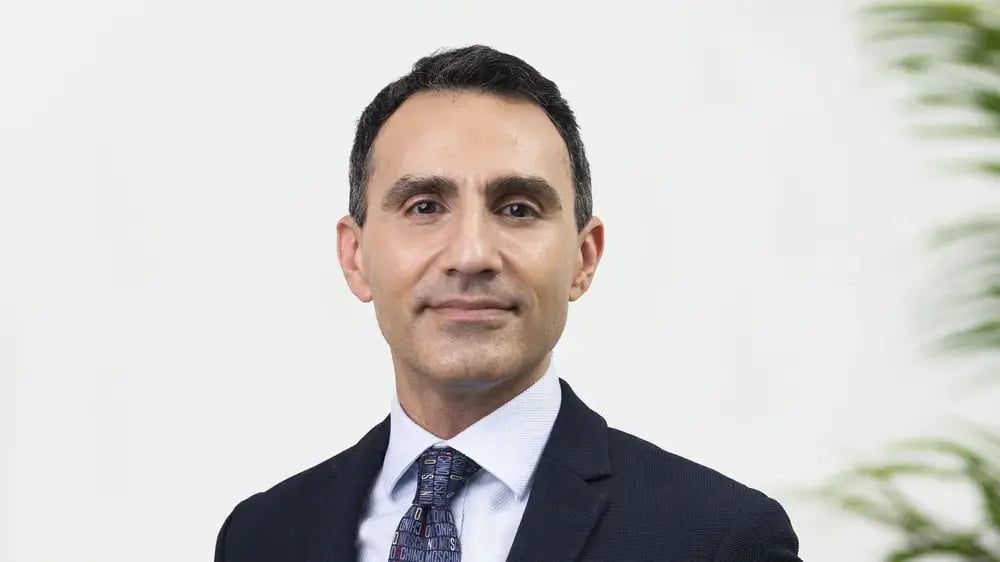
Panagiotis Kiziris
Director | FMIs
Explore our latest insights
Nov 3, 2026
Who Holds the Keys?
When I was a young officer, I learned that no armoury opens to one man. There were two keys, held by...
Nov 2, 2026
Other People’s Networks: What October’s Cyber Incidents Mean for Private Equity
October’s most consequential incidents shared one feature. The point of failure sat outside the vict...
Oct 30, 2026
Binance Hack: $6.3bn Theft Tests Digital Asset Resilience
30 October 2026 — based on information available at the time of writing.